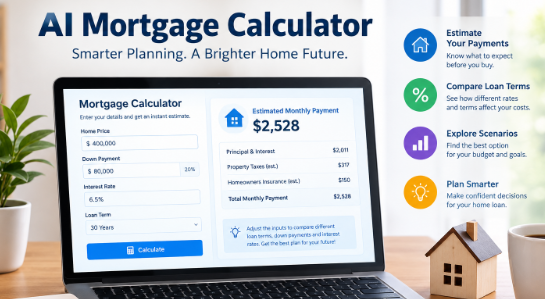
AI Mortgage Calculator helps estimate home loan payments, compare mortgage terms, explore costs, and plan smarter with clear, practical mortgage scenarios.
AI Mortgage Calculator
Buying a home is a major financial decision, and understanding the numbers before speaking with a lender can make the process much clearer. An AI Mortgage Calculator can help you estimate mortgage payments, compare different loan scenarios, and understand how changes in the home price, down payment, interest rate, or loan term can affect your budget.
A calculator is a planning tool rather than a loan approval tool. Your actual mortgage terms can depend on your lender, credit profile, property, loan program, taxes, insurance, fees, and other factors.
The Consumer Financial Protection Bureau (CFPB) also recommends looking beyond the principal-and-interest figure because a total monthly housing payment can include taxes, homeowners insurance, and mortgage insurance.
This guide explains how an AI Mortgage Calculator works, what information you should enter, how to interpret the results, and how AI-assisted calculations can make scenario planning easier.
Table of Contents
What Is an AI Mortgage Calculator?
An AI Mortgage Calculator is a digital tool designed to help users estimate mortgage-related costs using information such as the home price, down payment, interest rate, and loan term.
A conventional mortgage calculator generally follows a predefined mathematical formula. An AI-enhanced calculator may add a conversational interface or additional analysis that helps users understand the results and explore multiple scenarios.
For example, instead of entering one set of numbers and viewing a single payment, an AI-assisted tool could help you compare questions such as:
“What happens if I increase my down payment?”
“How would my payment change with a 15-year loan?”
“What if the interest rate increases by one percentage point?”
“How much more interest would I pay over a longer loan term?”
The important distinction is that AI does not remove the need for accurate financial information. The quality of the result still depends on the assumptions and data being used.
A mortgage calculator can estimate a payment, but it does not automatically determine whether a particular mortgage is affordable for your entire household budget. The CFPB specifically notes that the amount a lender is willing to lend is not necessarily the same as what you can comfortably afford.
For that reason, an AI Mortgage Calculator is most useful as a planning and comparison tool.
How an AI Mortgage Calculator Works
At its basic level, mortgage calculation involves mathematics rather than artificial intelligence.
For a typical fixed-rate mortgage, the principal-and-interest payment depends primarily on three variables: the amount borrowed, the interest rate, and the repayment term. The CFPB explains that lenders use a standard mathematical formula to calculate principal and interest for most mortgages.
An AI-powered interface can make the process more interactive.
Imagine that you are considering a $400,000 home. You have a $80,000 down payment and are evaluating a fixed-rate mortgage. You could enter the home price, down payment, interest rate, and loan term into a calculator.
The calculator can then estimate the loan amount and monthly principal-and-interest payment.
From there, you can change individual assumptions and compare scenarios.
This is where AI can potentially add convenience. Rather than manually calculating every scenario, an AI-based system can help organize questions around the numbers and explain how changing one input affects another.
However, an AI calculator should not be treated as a lender, broker, financial adviser, or source of guaranteed loan terms.
The final figures you receive from a lender can differ because of taxes, insurance, fees, mortgage insurance, rate changes, loan-program requirements, and other factors.
What Information Do You Need?
Before using an AI Mortgage Calculator, gather the basic information that will determine your estimated payment.
The home price is the starting point. This represents the purchase price of the property you are considering.
Next is the down payment. A larger down payment generally means you borrow less money, which can reduce the principal-and-interest payment and the total interest paid over the life of the loan.
The interest rate is another major input. Even a relatively small difference in the rate can have a substantial effect on a long-term mortgage because interest is calculated over many monthly payments.
You also need the loan term. Common examples include 15-year and 30-year mortgages in the United States, although available terms vary by lender and loan product.
Some calculators also allow you to enter annual property taxes, homeowners insurance, mortgage insurance, and homeowners association fees.
These additional inputs matter because the principal-and-interest figure does not necessarily represent the complete monthly cost of owning the home.
The CFPB describes PITI as principal, interest, taxes, and insurance and notes that these are basic components of a monthly mortgage payment.
A more detailed calculator may therefore provide a more useful budgeting estimate than one that shows principal and interest alone.
How Mortgage Payments Are Calculated
Understanding the basic calculation helps you interpret what an AI Mortgage Calculator is showing.
For a standard fixed-rate mortgage, the monthly principal-and-interest payment can be calculated using an amortization formula.
The formula is commonly represented as:
M = P × [r(1+r)ⁿ] / [(1+r)ⁿ − 1]
Here, M represents the monthly principal-and-interest payment.
P represents the principal, or amount borrowed.
r represents the monthly interest rate.
n represents the total number of monthly payments.
For example, a 30-year mortgage has 360 monthly payments.
The calculation does not mean that your entire housing expense is necessarily represented by M. Property taxes, homeowners insurance, mortgage insurance, HOA dues, and other expenses may be separate.
The CFPB warns that borrowers can underestimate their actual monthly housing cost if they look only at principal and interest.
That distinction is important when using an AI Mortgage Calculator to create a household budget.
7 Smart Ways to Use an AI Mortgage Calculator
1. Estimate Your Monthly Mortgage Payment
The simplest use of an AI Mortgage Calculator is estimating the monthly payment associated with a particular loan scenario.
Enter your estimated purchase price, down payment, interest rate, and loan term. The tool can then provide an estimated principal-and-interest payment.
If the calculator supports additional costs, enter property taxes and homeowners insurance as well.
This gives you a starting point for understanding the potential monthly commitment.
Remember that an estimate is not a loan offer. Freddie Mac similarly describes its fixed-rate mortgage calculator as a source of guidance and financial estimates and advises users to contact a lender for precise calculations.
2. Compare Different Down Payments
Your down payment can change the amount you need to borrow.
Suppose you are comparing a $40,000 down payment with an $80,000 down payment on the same property. Increasing the down payment reduces the initial loan balance, assuming all other factors remain unchanged.
An AI Mortgage Calculator can make this comparison easier because you can create multiple scenarios and examine the difference.
The useful question is not simply whether a larger down payment reduces the mortgage balance. You should also consider how much cash you want to retain for closing costs, emergency savings, moving expenses, repairs, and other financial needs.
The calculator can show the mathematical difference. Your personal budget determines what that difference means for you.
3. Compare 15-Year and 30-Year Terms
Loan duration can significantly affect both monthly payments and total interest.
A shorter loan term generally requires larger monthly principal-and-interest payments, but the loan is repaid over fewer months.
A longer term generally spreads repayment over more months, which can reduce the scheduled monthly principal-and-interest payment while increasing the amount of interest paid over the full term, assuming the rate and other assumptions are comparable.
An AI Mortgage Calculator can help you compare the two scenarios without manually repeating the calculation.
The key is to examine more than the monthly payment. Look at the total interest and total repayment as well.
4. Test Interest-Rate Changes
Interest rates are one of the most important variables in mortgage planning.
You can use an AI Mortgage Calculator to model several rates and see how the estimated payment changes.
For example, you could compare the same loan at 5%, 6%, and 7%.
This does not predict future interest rates. Instead, it demonstrates how sensitive your potential payment is to the rate assumption.
That can be particularly useful when you are building a household budget.
A calculator can show the numerical effect of a rate change, while a lender can provide information about the actual rates and loan products available to you.
5. Understand Your Total Monthly Housing Cost
A mortgage payment is not always the same thing as the complete cost of owning a home each month.
Depending on the property and mortgage, you may also have property taxes, homeowners insurance, mortgage insurance, HOA dues, and other expenses.
The CFPB identifies principal, interest, mortgage insurance, property taxes, and homeowners insurance among the costs that can affect the monthly housing payment. HOA fees may be separate.
This makes the total-payment view particularly useful.
If your AI Mortgage Calculator supports these fields, enter realistic estimates rather than leaving them at zero simply to produce a lower-looking result.
For expenses that vary by location, obtain estimates from appropriate local or professional sources.
6. Explore Different Home Prices
You can also use an AI Mortgage Calculator before you start seriously shopping for a property.
For example, you might compare estimated payments for homes priced at $300,000, $350,000, and $400,000.
This does not tell you what you should spend.
Instead, it helps you understand the relationship between purchase price and estimated financing costs.
The CFPB recommends considering the total monthly home payment and your broader household budget when determining what you can afford.
That means an affordability exercise should include more than a lender’s maximum approval amount.
7. Build Multiple Mortgage Scenarios
One of the most useful applications of an AI Mortgage Calculator is scenario analysis.
Instead of asking, “What is my mortgage payment?” you can ask a broader question:
“How does my estimated housing cost change under different assumptions?”
You could create a conservative scenario using a higher interest rate, a realistic scenario based on a current lender estimate, and another scenario using a different down payment or loan term.
This approach helps you understand how sensitive the purchase is to changing assumptions.
It is especially useful because mortgage decisions involve uncertainty. Taxes can change, insurance premiums can change, and adjustable-rate products can behave differently from fixed-rate loans.
Scenario planning does not remove that uncertainty, but it can make the financial consequences easier to understand.
Understanding Principal, Interest, Taxes, and Insurance
The term PITI is useful when evaluating mortgage payments.
PITI stands for principal, interest, taxes, and insurance.
Principal is the amount borrowed to purchase the property.
Interest is the cost charged for borrowing that money.
Property taxes are ongoing taxes associated with owning the property.
Homeowners insurance provides coverage according to the applicable insurance policy.
These categories may appear together in a mortgage payment when taxes and insurance are handled through escrow.
However, not every mortgage payment has the same structure. The CFPB notes that some borrowers pay taxes and insurance through escrow while others may pay those expenses directly.
That is why it is important to understand exactly what your calculator includes.
If an AI Mortgage Calculator displays a low principal-and-interest number, do not automatically assume that number represents your complete monthly housing expense.
AI Mortgage Calculator vs. Traditional Mortgage Calculator
The mathematics behind a mortgage payment does not necessarily become different simply because an AI interface is involved.
A traditional calculator typically requires you to enter numbers and then returns the calculated result.
An AI-assisted calculator may provide a more conversational experience. It might help you interpret scenarios, compare inputs, or explain financial terminology in simpler language.
The benefit is primarily in interaction and analysis rather than replacing the underlying financial mathematics.
This distinction matters because users should still verify important figures.
AI-generated explanations can be useful, but an AI system can misunderstand an input, use an incorrect assumption, or present an estimate without accounting for a specific lender’s requirements.
For mortgage decisions, the calculator should therefore complement reliable documentation rather than replace it.
Example: Comparing Different Mortgage Scenarios
Consider a hypothetical home purchase with a $400,000 purchase price.
Assume a buyer has $80,000 available for the down payment, leaving a hypothetical $320,000 loan before considering other costs.
Now imagine comparing two repayment periods.
A 30-year loan spreads repayment across 360 monthly payments. A 15-year loan spreads repayment across 180 monthly payments.
If the interest rate is held constant for comparison, the 15-year structure generally produces a higher scheduled monthly principal-and-interest payment because the borrower must repay the principal over half as many months.
However, the shorter term also means the loan is scheduled to accumulate interest for fewer years.
The purpose of this example is not to tell you which term to choose. Instead, it demonstrates why an AI Mortgage Calculator can be useful for comparing scenarios.
You can also change the down payment and interest rate while keeping the other variables constant.
That creates a clearer picture of which assumptions have the largest effect on the result.
For an actual mortgage, use the rate, fees, taxes, insurance, mortgage insurance, and loan terms provided by the relevant lender or other reliable sources.
Common Mistakes to Avoid
One common mistake is treating the calculator’s result as a guaranteed mortgage payment.
A calculator produces an estimate based on the information entered. A lender’s final figures can include additional costs and conditions.
Another mistake is ignoring property taxes and insurance.
A principal-and-interest payment can look manageable until additional housing costs are included. The CFPB specifically advises consumers to consider the total monthly payment rather than focusing only on principal and interest.
It is also easy to enter an unrealistic interest rate.
When you are planning an actual purchase, use a rate that reflects the mortgage product and assumptions you are researching. If you are stress-testing your budget, clearly label higher-rate scenarios as hypothetical.
Another mistake is focusing only on monthly affordability.
Two mortgages can have similar monthly payments but different total interest costs, fees, terms, or risk characteristics.
Finally, avoid assuming that an AI-generated recommendation is personalized financial advice. An AI system may not know your complete financial circumstances or the full terms of a loan offer.
How to Use AI Tools Responsibly for Mortgage Planning
An AI Mortgage Calculator can be useful when you use it as part of a broader research process.
Start with accurate inputs.
Then compare several scenarios rather than relying on a single result.
After that, verify important information against primary sources, lender documents, and other authoritative resources.
For example, the CFPB explains mortgage costs and payment components, while Freddie Mac provides a fixed-rate mortgage calculator intended for estimates and guidance.
You can also use other AI-powered productivity tools when preparing your research. For example, Copy.ai’s AI tools provides a collection of AI writing and productivity tools. It can be useful for organizing notes or drafting questions, but it should not be treated as a source of authoritative mortgage terms.
For the broader AI-tool ecosystem, you can also explore AI Tool Synergy and use relevant tools according to their actual capabilities.
The important principle is simple: use AI to make research and comparison easier, while verifying consequential financial information through appropriate authoritative sources.
Frequently Asked Questions About AI Mortgage Calculators
What is an AI Mortgage Calculator?
An AI Mortgage Calculator is a digital mortgage-planning tool that can estimate loan payments and, depending on its features, help users compare scenarios or understand the results through an AI-assisted interface.
Is an AI Mortgage Calculator accurate?
It can provide mathematically accurate estimates when the underlying formula and inputs are correct. However, the result may not equal a lender’s final payment because actual mortgages can include taxes, insurance, mortgage insurance, fees, changing rates, and other loan-specific factors.
Can an AI Mortgage Calculator tell me how much house I can afford?
It can help you model affordability scenarios, but it cannot independently determine your complete financial capacity. Your income, existing debts, savings, recurring expenses, emergency reserves, taxes, insurance, and other circumstances matter.
The CFPB also distinguishes between how much a lender may be willing to lend and how much a borrower can comfortably afford within their overall budget.
What should I enter into an AI Mortgage Calculator?
Typical inputs include the home price, down payment, interest rate, and loan term. More comprehensive calculators may also request property taxes, homeowners insurance, mortgage insurance, and HOA fees.
Does an AI Mortgage Calculator include taxes and insurance?
That depends on the calculator. Some calculators calculate only principal and interest, while others allow additional housing costs to be included. Always check which costs are included in the displayed result.
Can an AI Mortgage Calculator compare 15-year and 30-year loans?
Yes. If the calculator allows you to change the loan term, you can compare different repayment periods and examine how the estimated monthly payment and total interest change.
Can an AI Mortgage Calculator replace a mortgage lender?
No. A calculator provides estimates. A lender evaluates your application, loan program, property, documentation, eligibility, and other requirements before providing actual loan terms.
Should I use an AI Mortgage Calculator before applying for a mortgage?
It can be useful for preliminary planning because it allows you to explore different assumptions before contacting lenders. It should be treated as an educational and budgeting aid rather than an approval tool.
Final Thoughts
An AI Mortgage Calculator can turn a complicated mortgage calculation into a more understandable planning exercise. By changing the home price, down payment, interest rate, loan term, taxes, and insurance assumptions, you can see how different scenarios affect your estimated housing costs.
The biggest benefit is not simply getting one monthly number. It is understanding how the numbers interact.
Use the calculator to explore scenarios, check the impact of different assumptions, and prepare better questions for lenders. Then verify the important details using actual loan documents and authoritative financial resources.
Mortgage calculations can provide valuable estimates, but they should always be interpreted in context. A monthly payment that looks affordable in a calculator may not account for every cost of homeownership, while a lender’s maximum qualification amount may not match what fits comfortably within your household budget.
Used carefully, an AI Mortgage Calculator can therefore be a practical starting point for understanding mortgage mathematics, comparing scenarios, and preparing for the home-buying process.